New JerseyInsurance Appraiser (844) 537-1427

Independent appraisal · All 21 counties

New Jersey Insurance Appraiser: a second, independent number for claims that came up short

When your insurer accepts the claim but the check won’t cover the repair, New Jersey Insurance Appraiser builds a line-by-line valuation of the damage and carries it through the appraisal process written into your policy.

  • Roofs & hail
  • Nor’easters
  • Ice dams
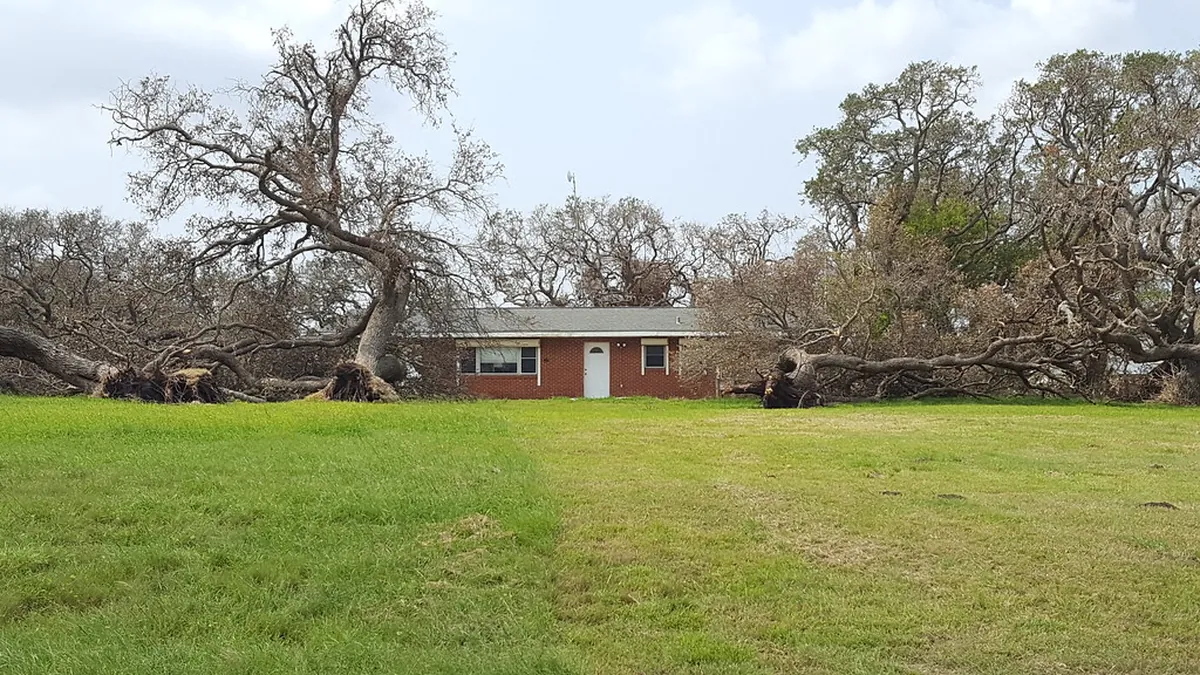
  • Fallen trees
  • Fire & smoke
  • Condo & HOA
Free claim review

Is your settlement short?

Two minutes. We call back within one business day.

No obligation. Your details stay private.

21New Jersey counties served
564municipalities, one standard of work
12appraisal & estimating services
7free claim tools, nothing stored
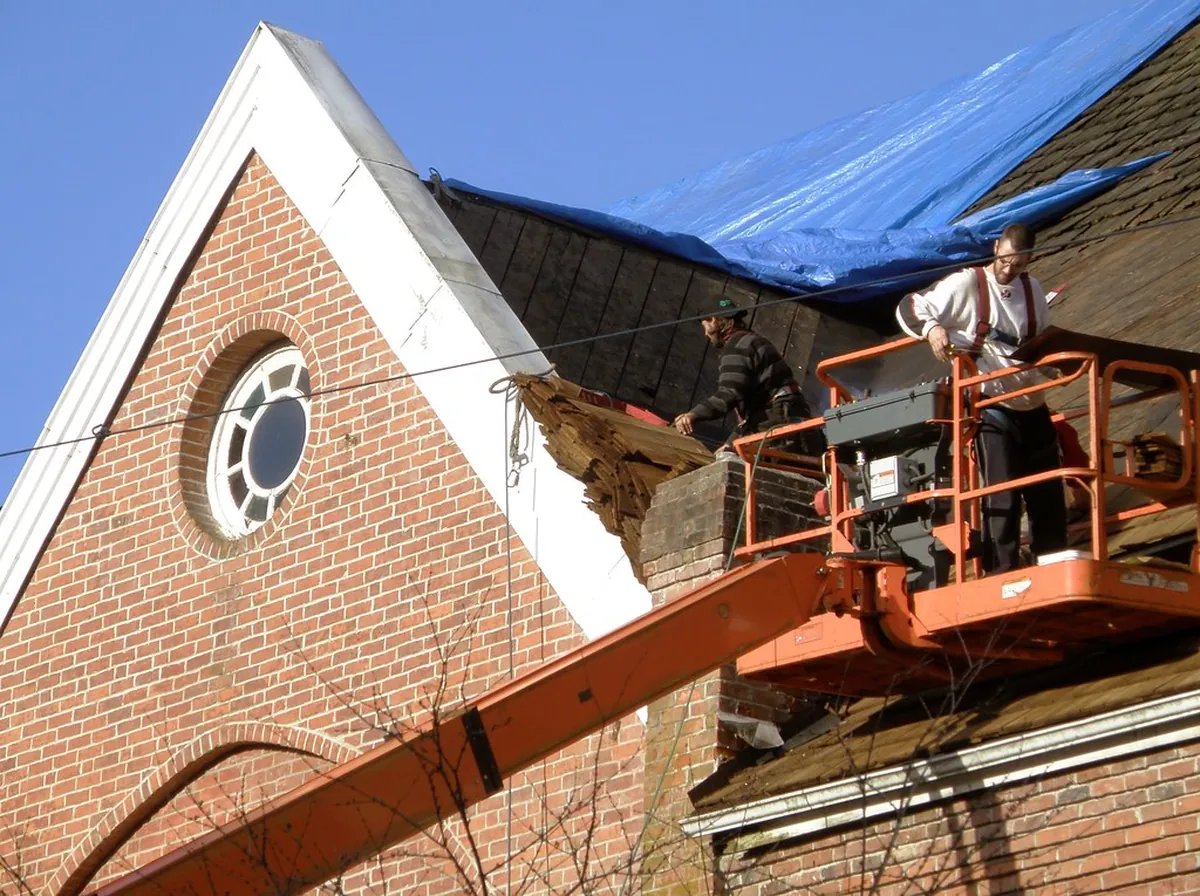
Roofers on a lift repairing a damaged brick building covered with a blue tarp
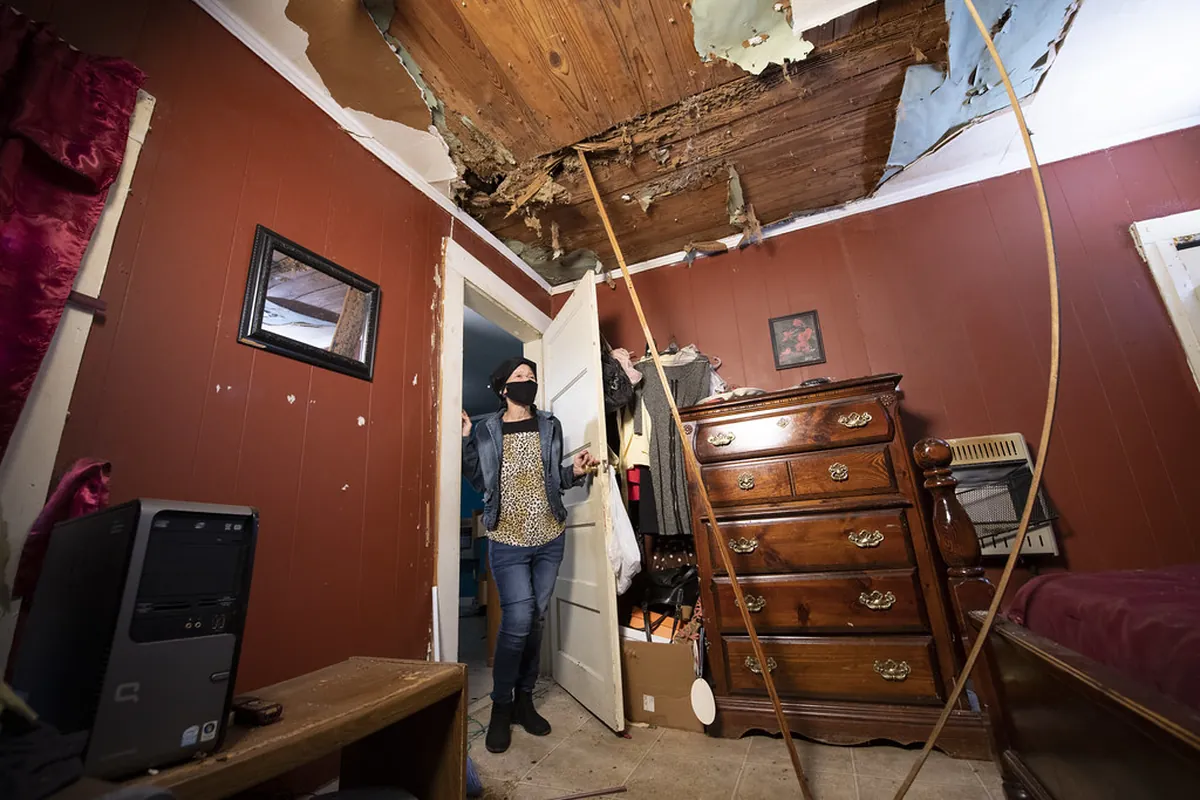
Bedroom with a collapsed, water-damaged ceiling

Covered ≠ paid in full. Most short claims aren’t denied. They’re just missing pieces.

Why owners call

Why owners call a New Jersey Insurance Appraiser instead of arguing by phone

A missing roof slope. Plaster priced as drywall. A two-family house valued as one unit. Code items nobody counted. A New Jersey Insurance Appraiser exists for that space between “your claim is covered” and “your repair is paid for.”

  • We start from the property, not their estimate. Our own inspection, measurements and photos.
  • Numbers built to survive an umpire. Supportable beats inflated every time.
  • Straight answers on the first call. If you need an attorney or a simple supplement instead, we’ll say so.
How we work

Twelve services

What a New Jersey Insurance Appraiser can take off your plate

Every service is built around one job: an accurate valuation of your loss that holds up when the other side checks it. Start with an estimate review, or bring us in once appraisal has been demanded.

01

Appraisal Demand Representation

We act as the appraiser you name after either side makes a written appraisal demand.

Learn more
02

Homeowners Insurance Appraisal

Houses, townhomes and two-family homes where the carrier’s estimate leaves out real repair costs.

Learn more
03

Condo, HOA & Commercial Appraisal

Master policies, mid-rise condos, retail, warehouses and mixed-use buildings.

Learn more
04

Roof & Hail Damage Appraisal

Shingle, slate, cedar, flat and metal roofs, from a few cracked tabs to a full replacement.

Learn more
05

Wind & Tornado Damage Appraisal

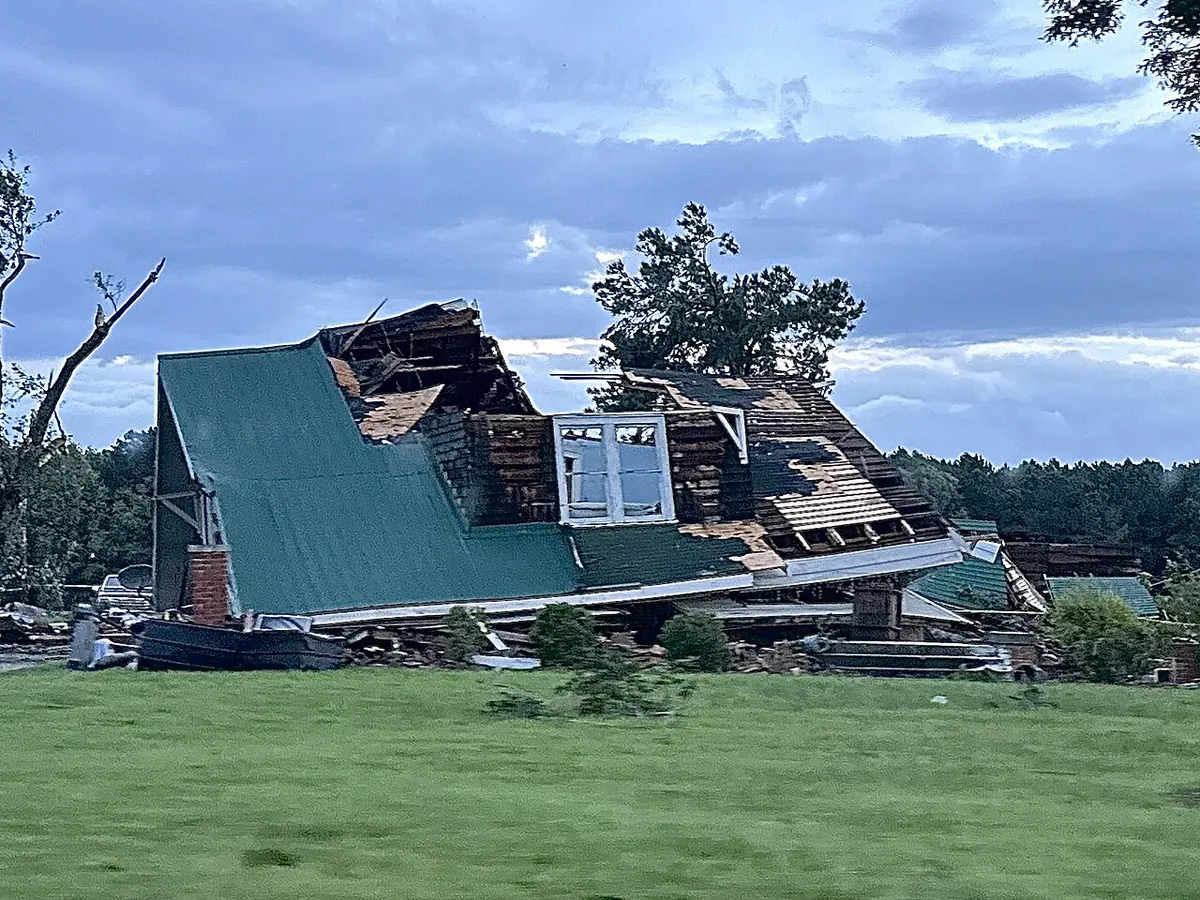
Derechos, squall lines and the rare New Jersey tornado: lifted shingles, siding, fences and structure.

Learn more
06

Hurricane & Nor’easter Claim Appraisal

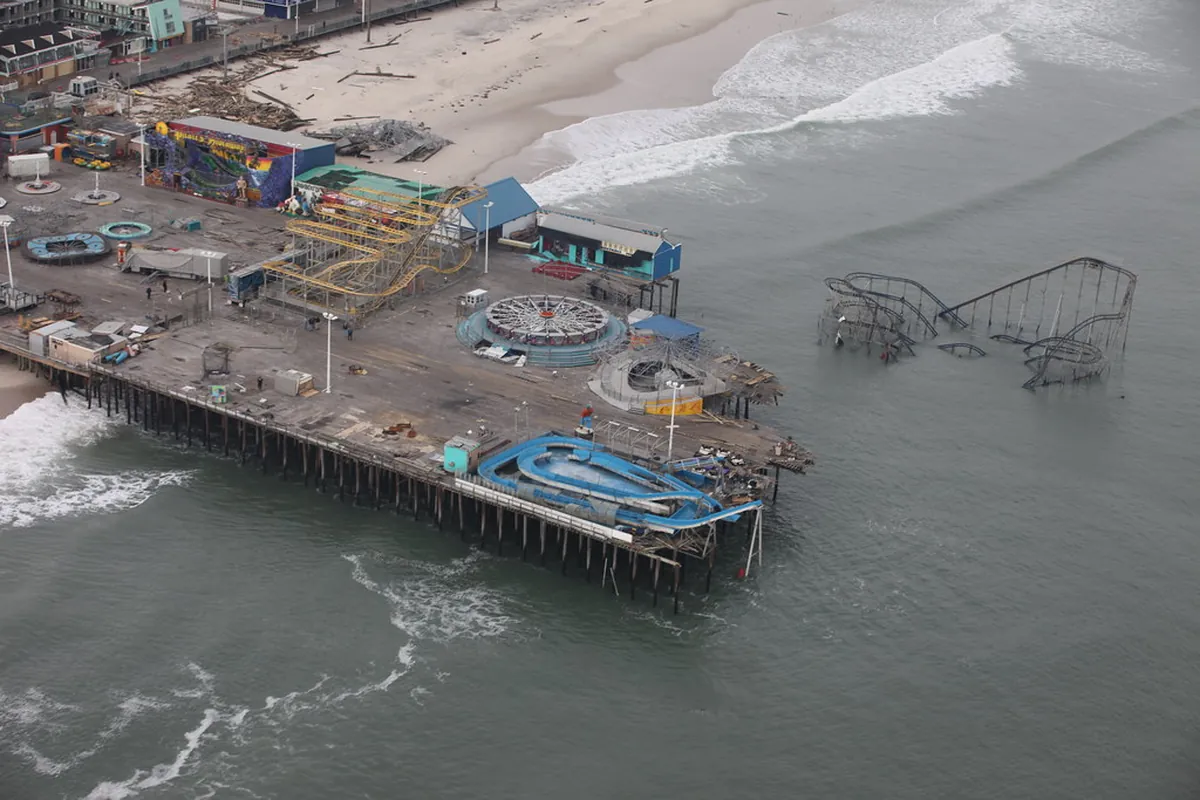
Coastal storms from Sandy to the latest nor’easter: wind, wind-driven rain and wind-versus-flood splits.

Learn more
07

Water, Ice Dam & Pipe Burst Appraisal

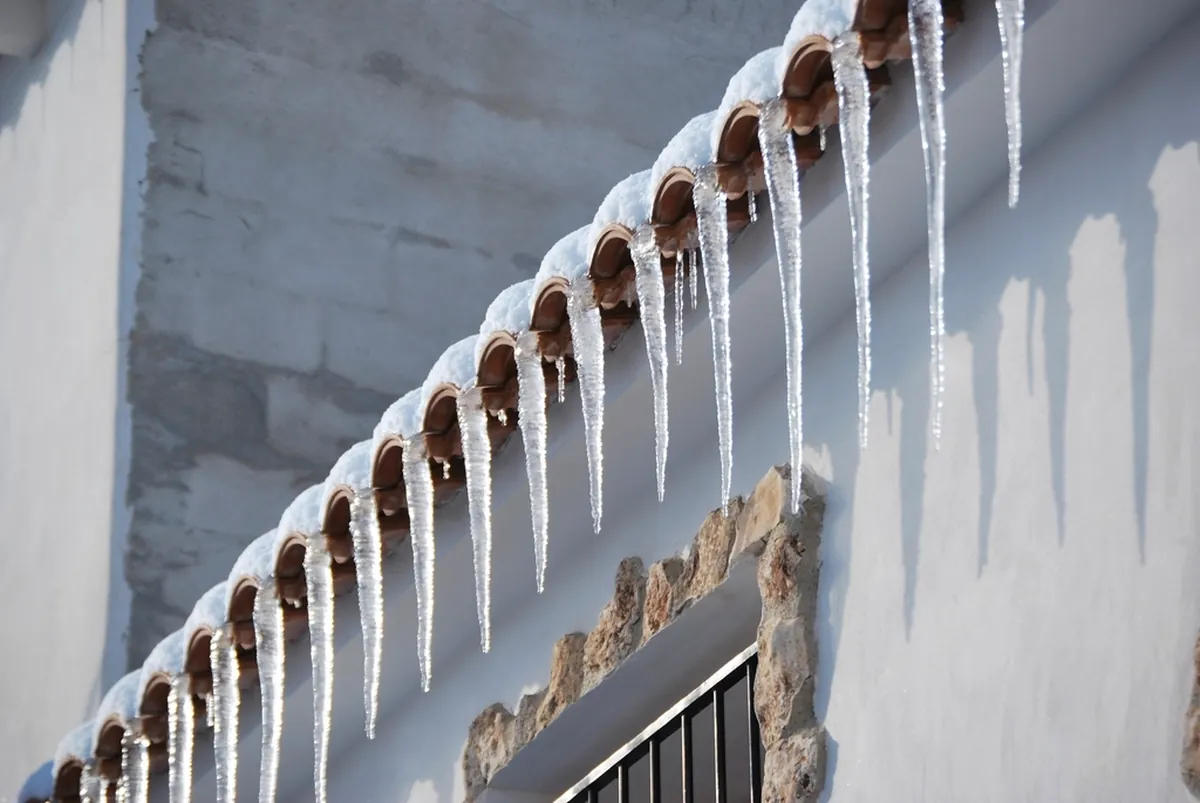
Burst pipes, ice dams, appliance leaks and condo water that moves from unit to unit.

Learn more
08

Fire & Smoke Loss Appraisal

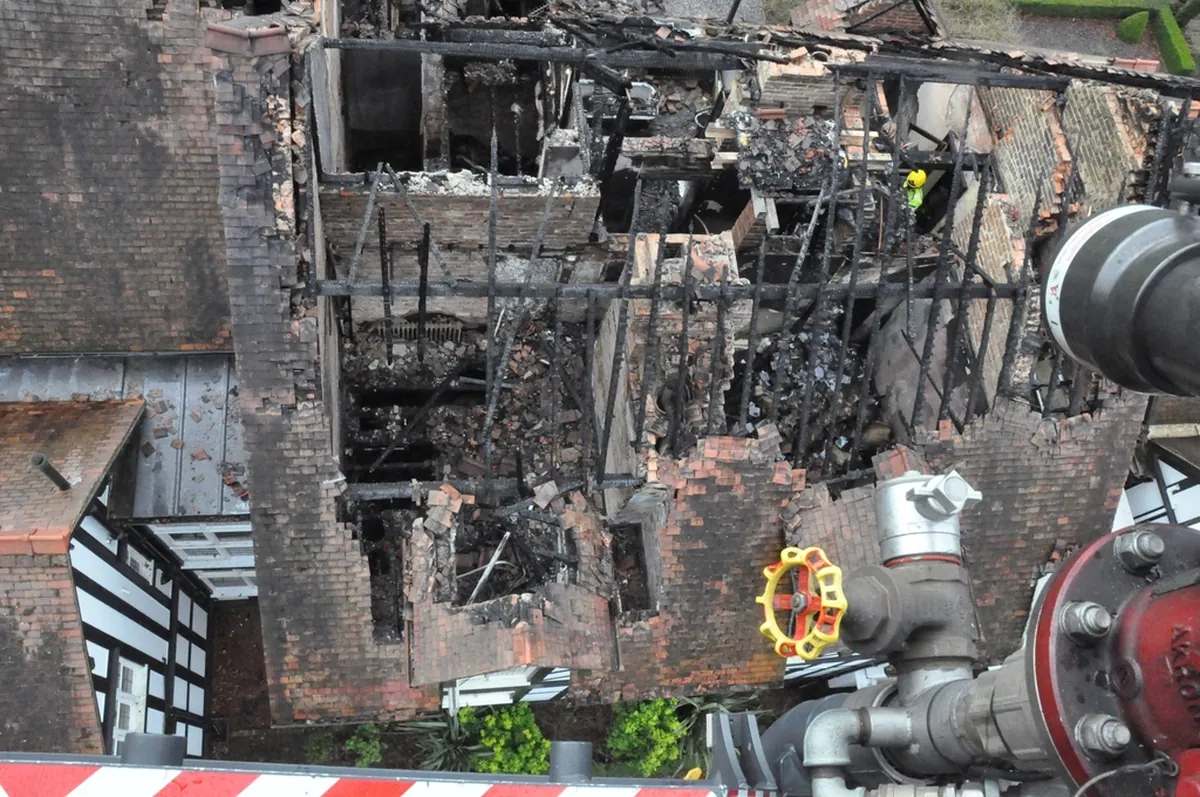
Kitchen fires to total losses, with smoke, soot and odor that travel far beyond the burn.

Learn more
09

Pinelands Wildfire & Smoke Appraisal

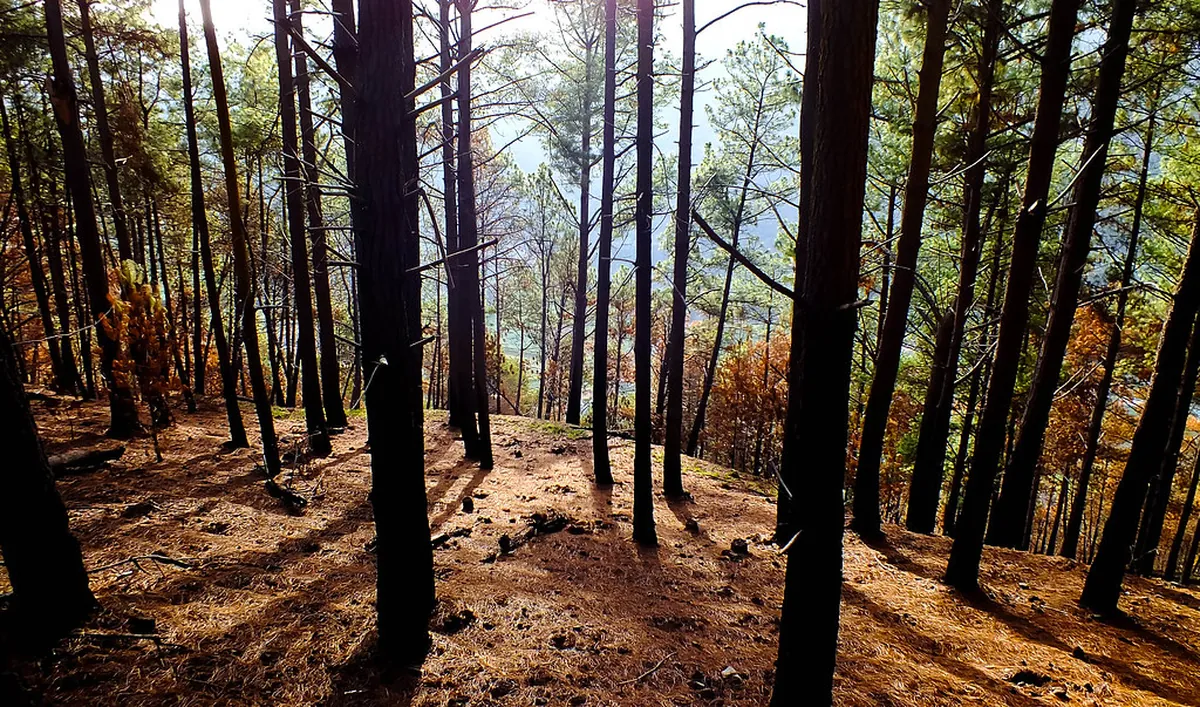
Ember, heat and smoke damage for homes and businesses near the Pine Barrens.

Learn more
10

Tree Fall & Ice Storm Appraisal

Mature oaks and maples on roofs, cars and fences after nor’easters, ice storms and summer squalls.

Learn more
11

Carrier Estimate Review

A line-by-line review of the insurer’s estimate before you accept, supplement or invoke appraisal.

Learn more
12

Neutral Umpire Services

Impartial umpire work for appraisal panels that need a neutral third member.

Learn more

Storm record

Eight storms that taught a New Jersey Insurance Appraiser what to look for

New Jersey’s big losses rarely fit the textbook. Each of these events changed how claims are scoped, split between policies or argued.

  1. 1962

    Ash Wednesday Storm

    A three-day nor’easter reshaped the shore. Lesson: nor’easters can do hurricane-scale damage without a hurricane deductible.

  2. 1999

    Tropical Storm Floyd

    Record flooding along the Raritan basin. Lesson: inland homes need flood coverage too.

  3. Aug 2011

    Hurricane Irene

    Came ashore near Little Egg Inlet and flooded river towns. Lesson: wind and water claims arrive together.

  4. Oct 2011

    Halloween nor’easter

    Heavy snow on leafy trees across North Jersey. Lesson: debris limits rarely cover big trees.

  5. Jun 2012

    South Jersey derecho

    Straight-line winds toppled trees and roofs in minutes. Lesson: document wind damage before cleanup.

  6. Oct 2012

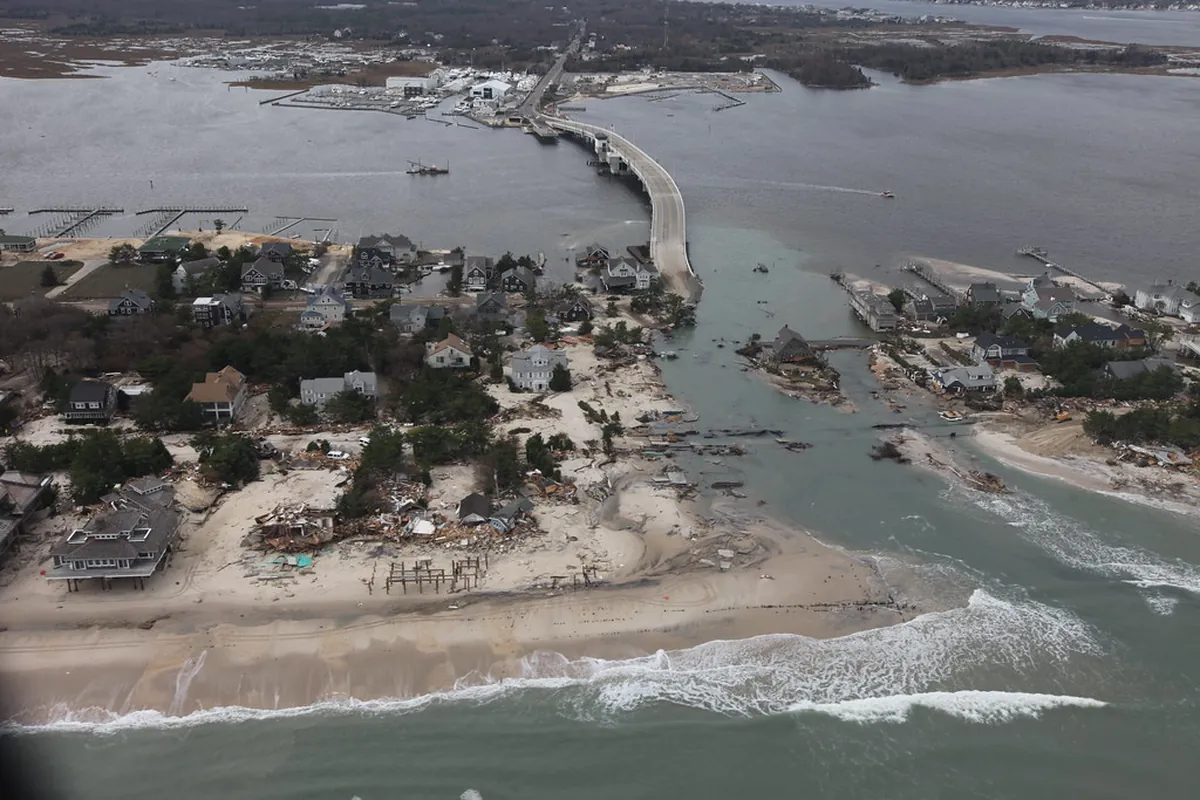
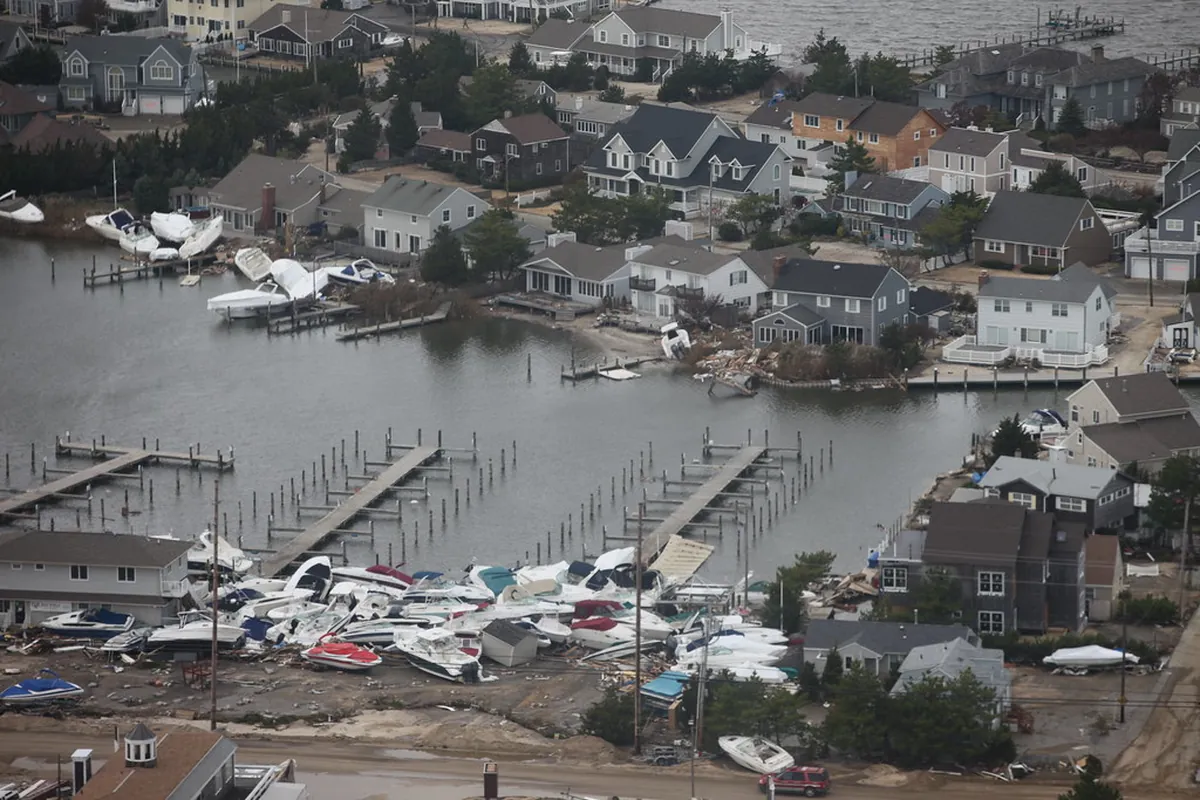
    Superstorm Sandy

    Landfall near Brigantine and record surge. Lesson: hurricane deductibles depend on exact trigger wording.

  7. Sep 2021

    Ida’s remnants

    Flash floods and the Mullica Hill tornado. Lesson: basement water is often a flood or endorsement question.

  8. Apr 2025

    Jones Road Wildfire

    About 15,000 acres burned in Ocean County. Lesson: smoke damage reaches homes the fire never touched.

The process

Seven steps from a short estimate to a signed award

The appraisal clause turns an open-ended argument into a defined process with a binding result. This is how a New Jersey Insurance Appraiser moves a file from first call to award.

Read the full process guide
  1. 1

    Put the disagreement on paper

    Appraisal starts with a claim that has been accepted, at least in part.

  2. 2

    Make the written demand

    If the gap remains, either side can demand appraisal in writing.

  3. 3

    Each side names an appraiser

    Under language based on New Jersey’s standard fire policy, each side commonly has 20 days from the demand to name a competent and disinterested appraiser.

  4. 4

    The appraisers choose an umpire

    The two appraisers pick a neutral umpire, often early so one is ready if needed.

  5. 5

    The appraisers work the differences

    This is where most of the work happens.

  6. 6

    The umpire decides what’s left

    Items the appraisers can’t settle go to the umpire.

  7. 7

    The award is signed and paid

    An award signed by any two of the three sets the amount of loss.

Five regions

From the Skylands to Cape May, a New Jersey Insurance Appraiser prices local damage

The same policy language plays out differently in a Paterson two-family, a Morristown Victorian and an Ocean City duplex. A New Jersey Insurance Appraiser has to know how each region’s weather shows up on a roof and in an estimate.

Bergen · Essex · Hudson · Passaic · Union

Gateway North Jersey

The most densely built part of the state, from Hudson River condo towers to Paterson’s multi-family blocks. Claims here often involve several units, shared roofs and water that moves between floors.

  • River & flash flooding
  • Multi-family water losses
  • Flat roofs
  • Condo towers

Towns: Newark, Jersey City, Paterson, Hackensack, Elizabeth, Hoboken
Morris · Sussex · Warren · Hunterdon

Skylands & Highlands

Higher ground and colder winters. Heavy wet snow, ice storms and big hardwoods make tree and winter water losses the main event, as the Halloween nor’easter of 2011 showed.

  • Ice dams
  • Heavy snow
  • Tree fall
  • Frozen pipes

Towns: Morristown, Parsippany, Newton, Flemington, Phillipsburg

Middlesex · Somerset · Mercer

Central Jersey

The Raritan basin floods in big tropical rains, from Floyd in 1999 to Ida in 2021. Postwar suburbs, Route 1 commerce and Trenton’s rowhouses fill the claim files.

  • Inland flooding
  • Wind & hail
  • Commercial roofs
  • Rowhouse fires

Towns: Edison, New Brunswick, Trenton, Princeton, Somerville, Bound Brook

Monmouth · Ocean · Atlantic · Cape May

The Jersey Shore

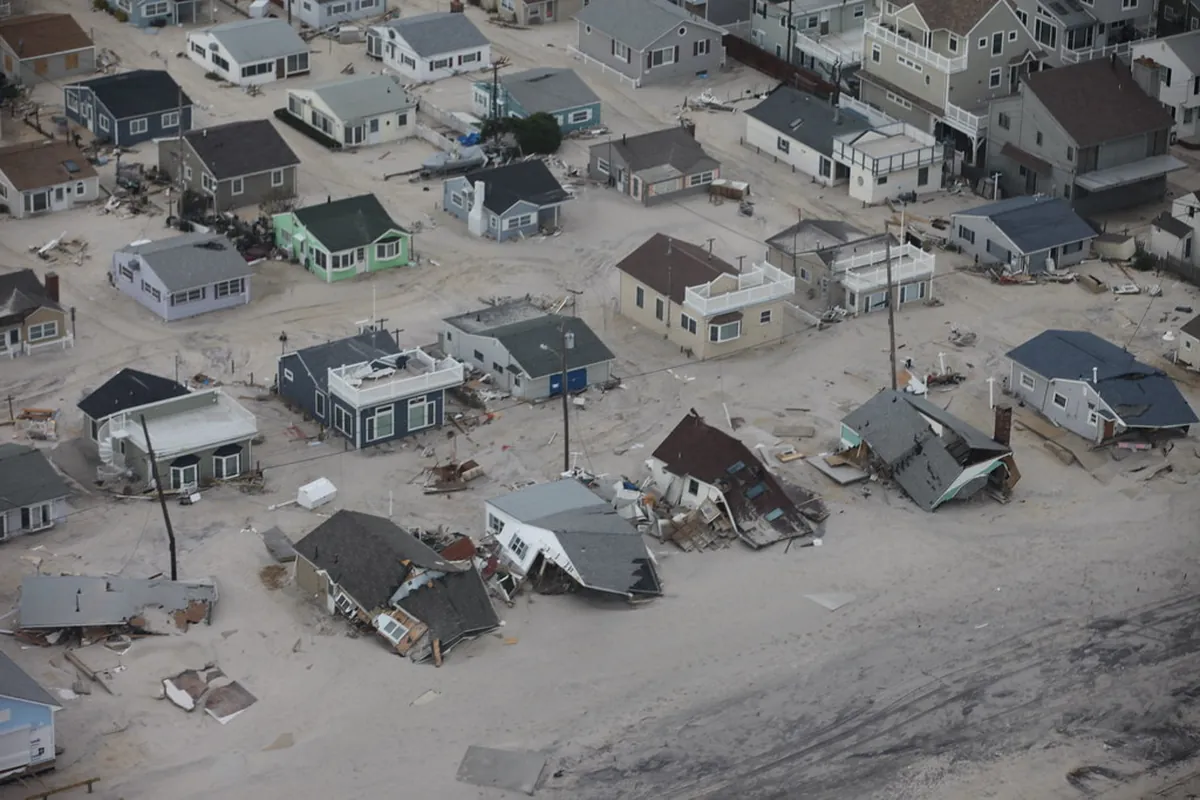
Barrier islands, bay towns and elevated rebuilds. Every major storm raises the same questions: which damage was wind, which was water, and which deductible applies.

  • Nor’easters
  • Wind vs. flood
  • Hurricane deductibles
  • Seasonal-home freezes

Towns: Long Branch, Toms River, Atlantic City, Ocean City, Cape May

Camden · Burlington · Gloucester · Salem · Cumberland

South Jersey & the Pinelands

Philadelphia suburbs give way to farms and the Pine Barrens. Derechos, the 2021 Mullica Hill tornado and Pinelands wildfires all shape claims here.

  • Derecho winds
  • Tornadoes
  • Wildfire smoke
  • Farm buildings

Towns: Cherry Hill, Mount Laurel, Mullica Hill, Vineland, Hammonton

Quick check

Is the gap big enough to appraise?

Type in the two numbers you already have. If the difference is large, a conversation with a New Jersey Insurance Appraiser makes sense. If it’s small, a documented supplement request may close it faster and cheaper.

The full claim gap & net recovery estimator adds appraiser and umpire fees and shows three outcomes.

60-second gap checkNo sign-up
50%
of the disputed amount
Amount in dispute$0
Gap vs. carrier estimate—
Projected award$0
Increase before fees$0

Choosing help

Appraiser, public adjuster or attorney?

Each solves a different problem. Picking the right one first saves time and fees, and a New Jersey Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.

QuestionNew Jersey Insurance AppraiserPublic adjusterAttorney
Main jobValue the amount of lossPrepare & negotiate the claimLegal disputes & lawsuits
Best stageCoverage accepted, number disputedEarly, from first noticeDenials, bad faith, deadlines
ResultBinding award (2 of 3 signatures)Negotiated settlementSettlement or judgment
Works forThe side that names them, or neither side as umpireThe policyholder, under a state licenseThe client

Questions

What people ask a New Jersey Insurance Appraiser

Straight answers about how appraisal works, what it costs and when it’s the wrong move.

What does a New Jersey Insurance Appraiser do?

We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your named appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present open items to a neutral umpire.

How is an appraiser different from a public adjuster?

A public adjuster is licensed by the state to manage and negotiate the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate claims outside appraisal, and we don’t give legal advice.

When should I call a New Jersey Insurance Appraiser?

When coverage is accepted, you have the carrier’s estimate, and the gap between it and your contractor’s number is meaningful, usually more than about 10% or several thousand dollars.

Is an appraisal award binding?

On the amount of loss, yes, once any two of the three panel members sign. That’s why the file should be complete before anyone demands appraisal.

What does it cost?

Each side pays its own appraiser and usually half of the umpire. We put our fee terms in writing before any work starts, and the first conversation is free.

Does a New Jersey Insurance Appraiser cover the whole state?

Yes. We work in all 21 counties, from Sussex and Bergen to Cumberland and Cape May.

Articles

Read this before you demand appraisal

Practical guides from the New Jersey Insurance Appraiser team on policy language, documentation and strategy.

All articles

Before you sign a release

Check the numbers while you still can

A short review now can keep you from accepting a settlement that won’t cover the work.

Start here

Talk to a New Jersey Insurance Appraiser about your claim

Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth it. No pressure, no obligation.

Tell us about your claim

Free review, no obligation. We usually reply within one business day.

Call now Free review